If I had a dollar for every time someone called our office and said “I think I missed my window for Medicare,” I’d have retired years ago. It’s the single most common question I field, and I get why. Medicare doesn’t work on one simple birthday deadline. There are several enrollment periods, they all have different rules, and missing the wrong one can cost you money for the rest of your life. So let’s clear this up.
Your first window: the Initial Enrollment Period
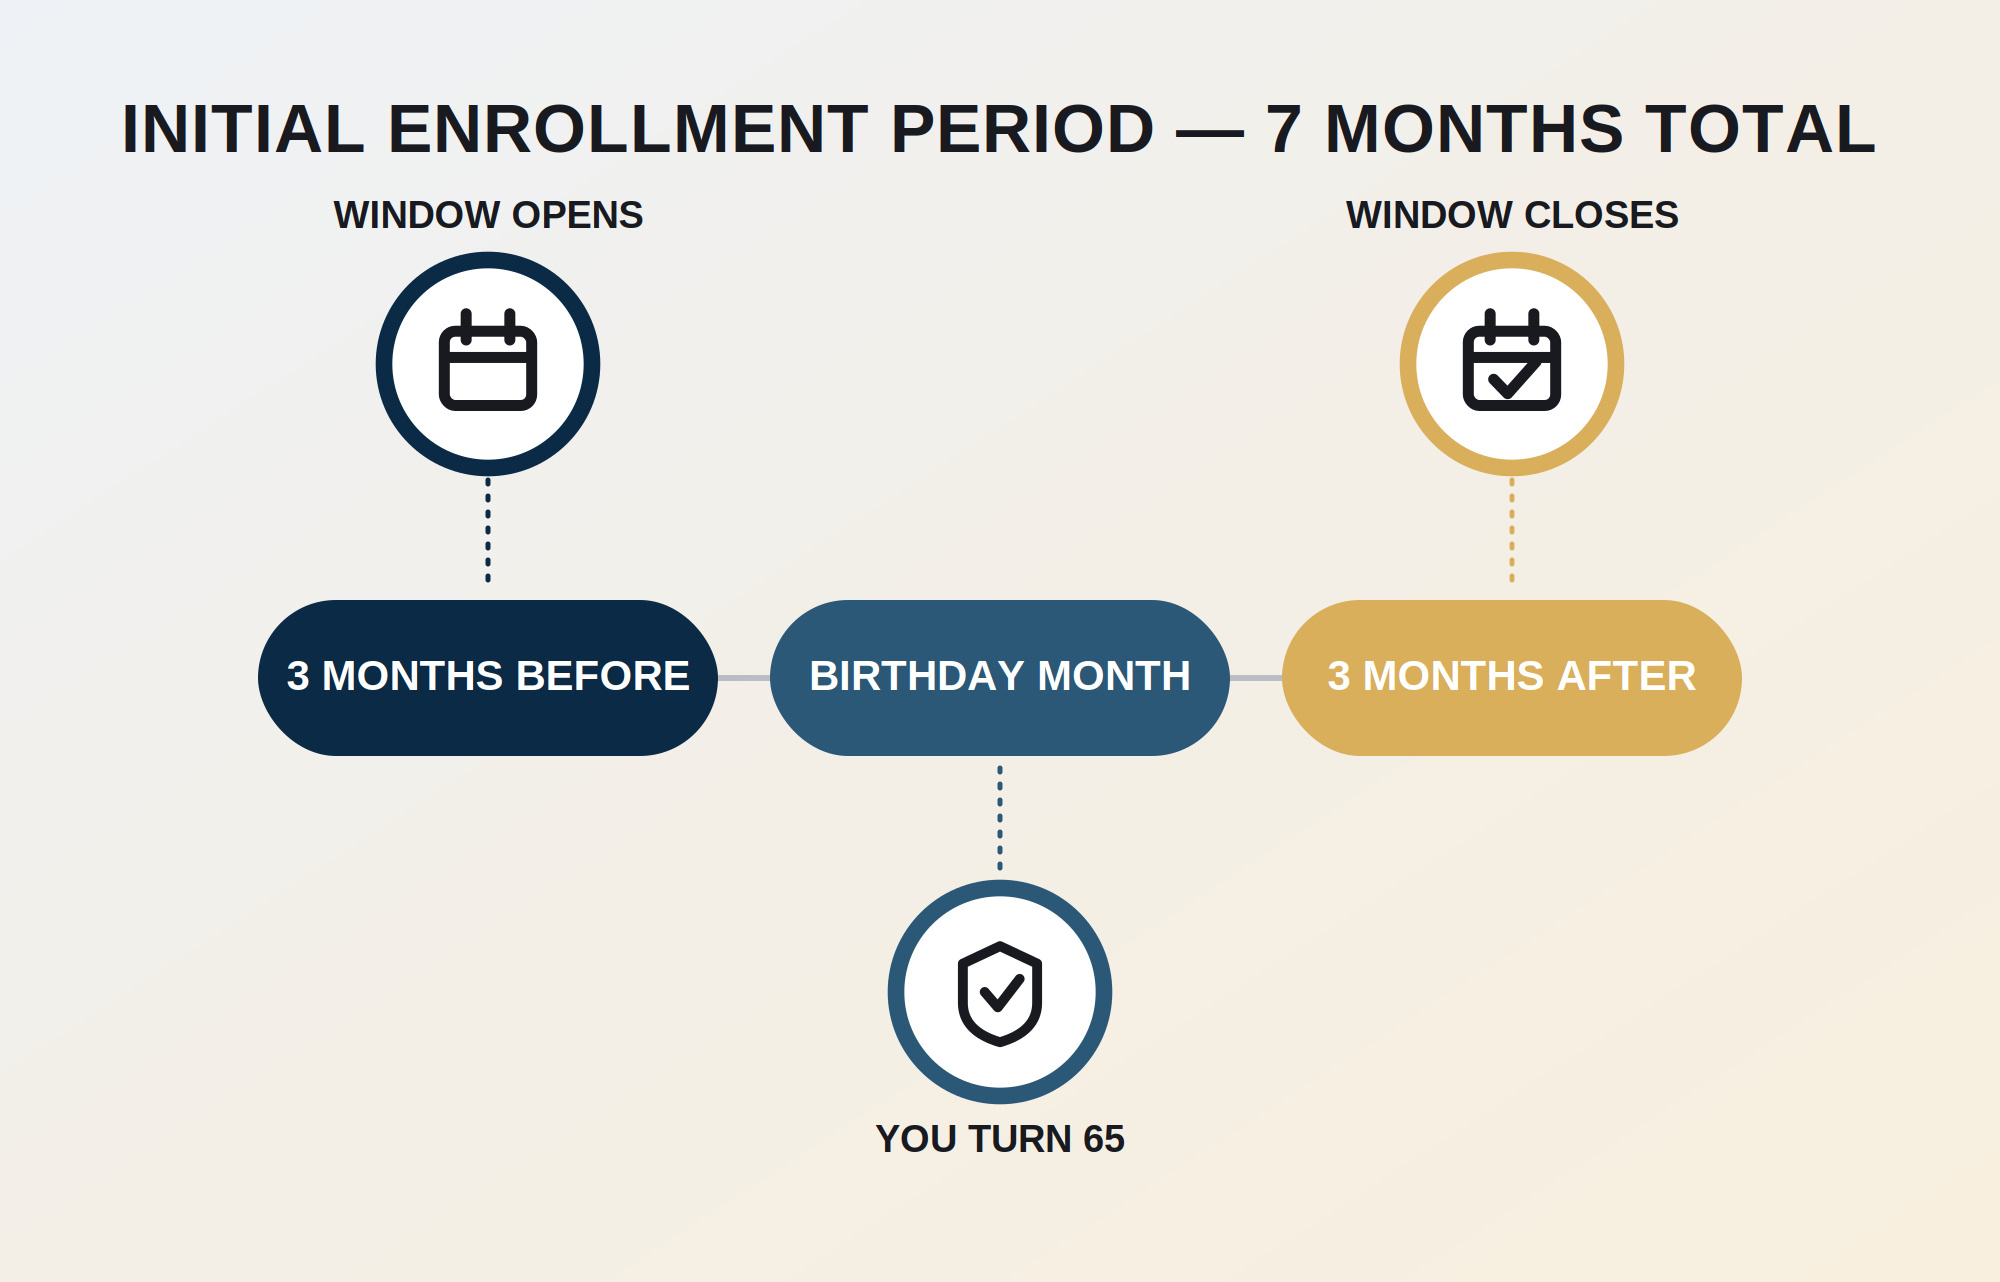
When you turn 65, you get a seven month window to sign up. It starts three months before your birthday month, includes your birthday month, and runs three months after. That’s your Initial Enrollment Period, or IEP, and it’s the cleanest, easiest way to get into Medicare with no penalties attached. You can see exactly how Social Security lays out this window on their Medicare enrollment page, which is also where you’ll actually apply. I tell every client the same thing: don’t wait until the month you turn 65 to start paying attention. Start the conversation at least four months out so you have time to actually think it through instead of scrambling.
If you miss it: the General Enrollment Period
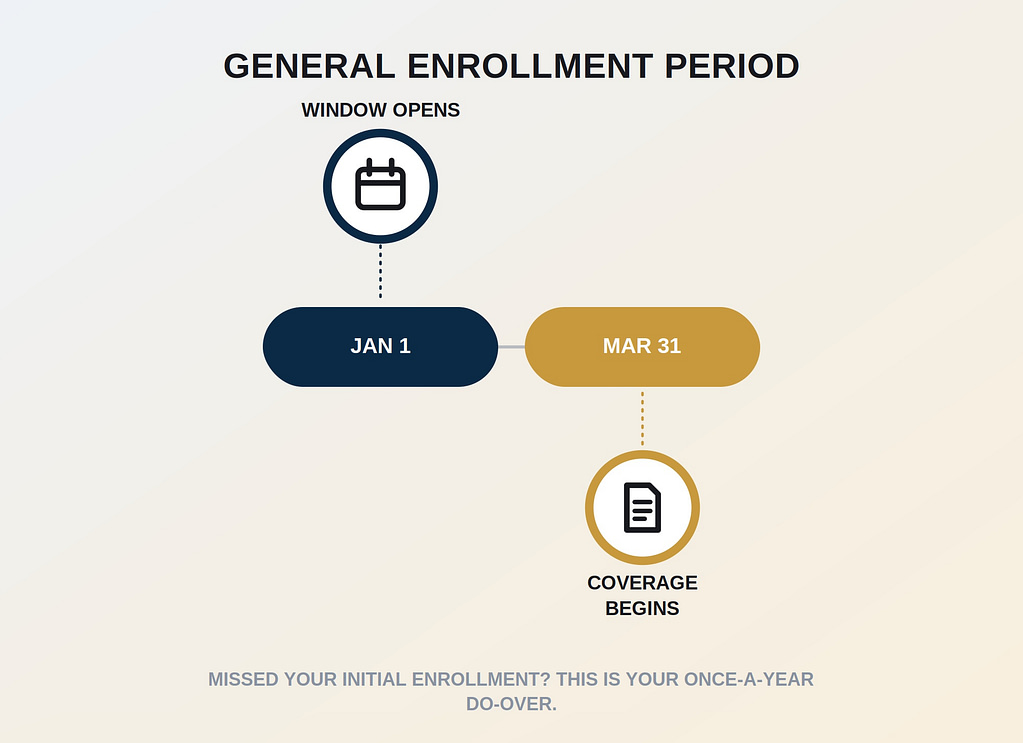
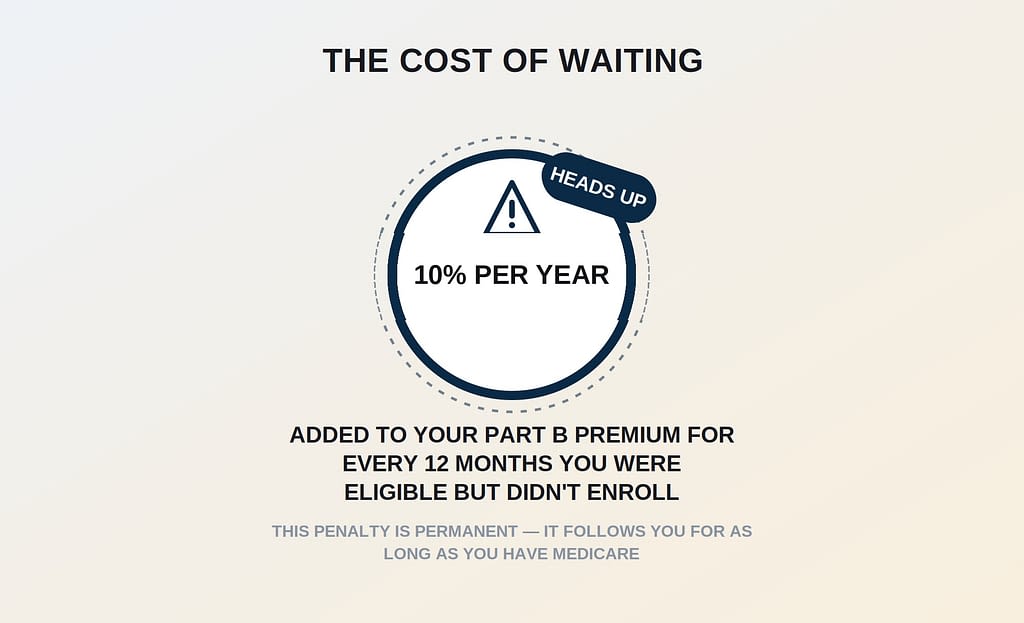
Life happens. People miss this window more often than you’d think, usually because nobody told them it existed. If that’s you, there’s a General Enrollment Period every year from January 1 through March 31, with coverage starting the month after you sign up. The catch is the late enrollment penalty. Part B carries a penalty of 10 percent for every 12 month period you were eligible but didn’t enroll, and that penalty typically sticks with you for as long as you have Medicare. Medicare.gov breaks down exactly how that penalty is calculated, including real dollar examples at current premium rates. This is exactly why I push people to plan ahead rather than assume they can fix it later.
If you’re still working: the Special Enrollment Period
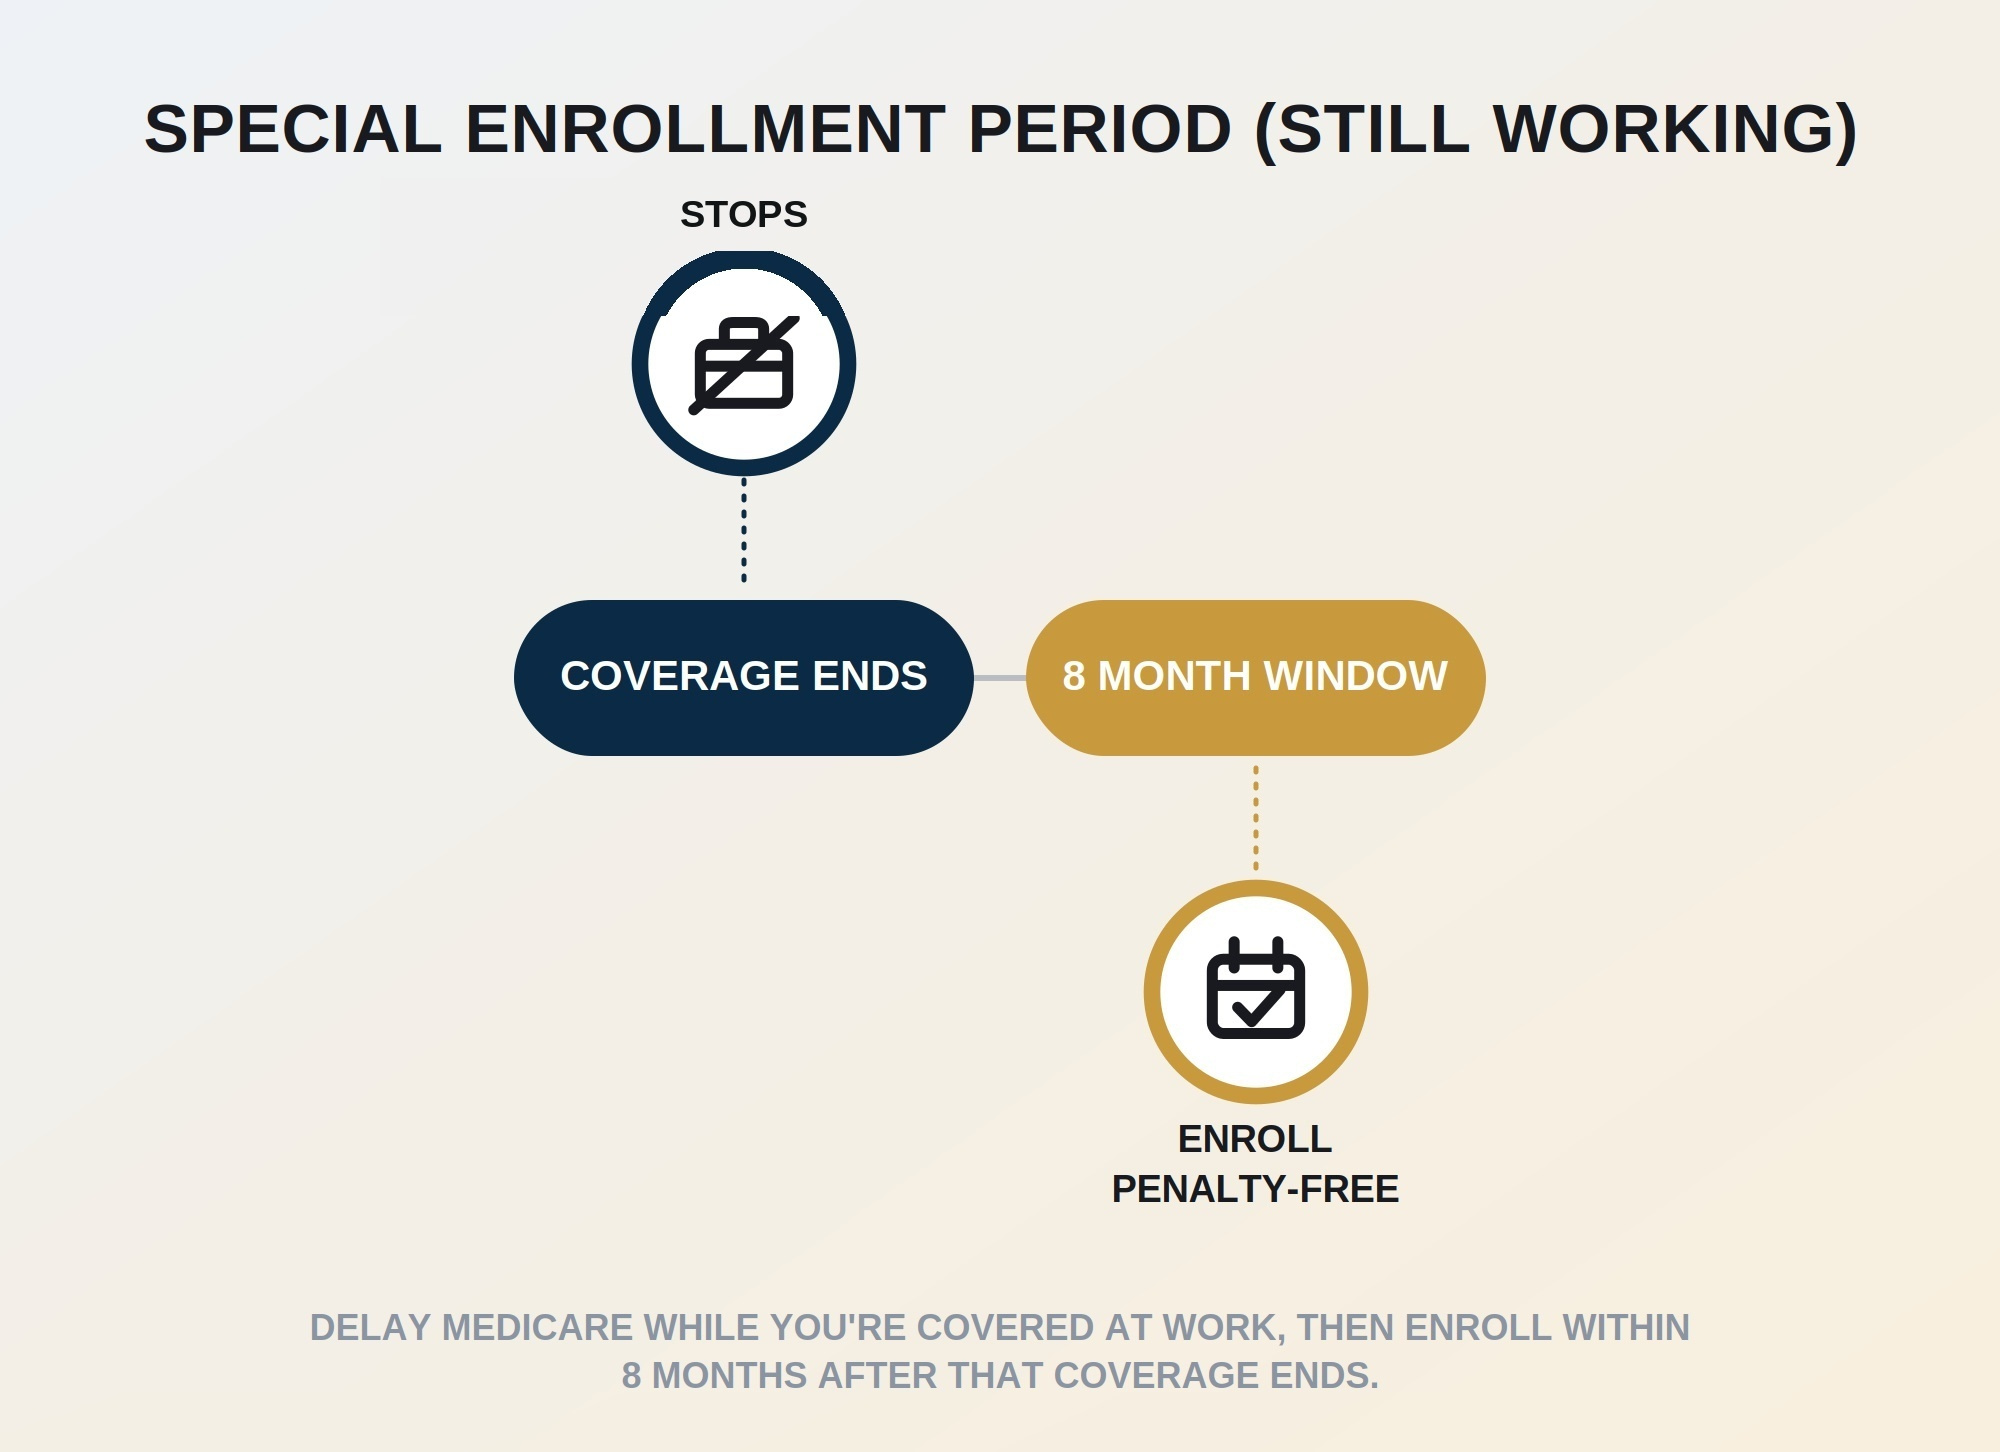
This is the one that trips people up the most, and it’s a topic I could write a whole separate post about. If you or your spouse are still working and covered by a group health plan through that employer, you may be able to delay Medicare without any penalty. Once that job based coverage ends, you get an eight month Special Enrollment Period to sign up. The Centers for Medicare & Medicaid Services lays out the full rules on Medicare.gov, and I’d encourage anyone in this situation to read it directly rather than guess.
Every fall: the Annual Enrollment Period
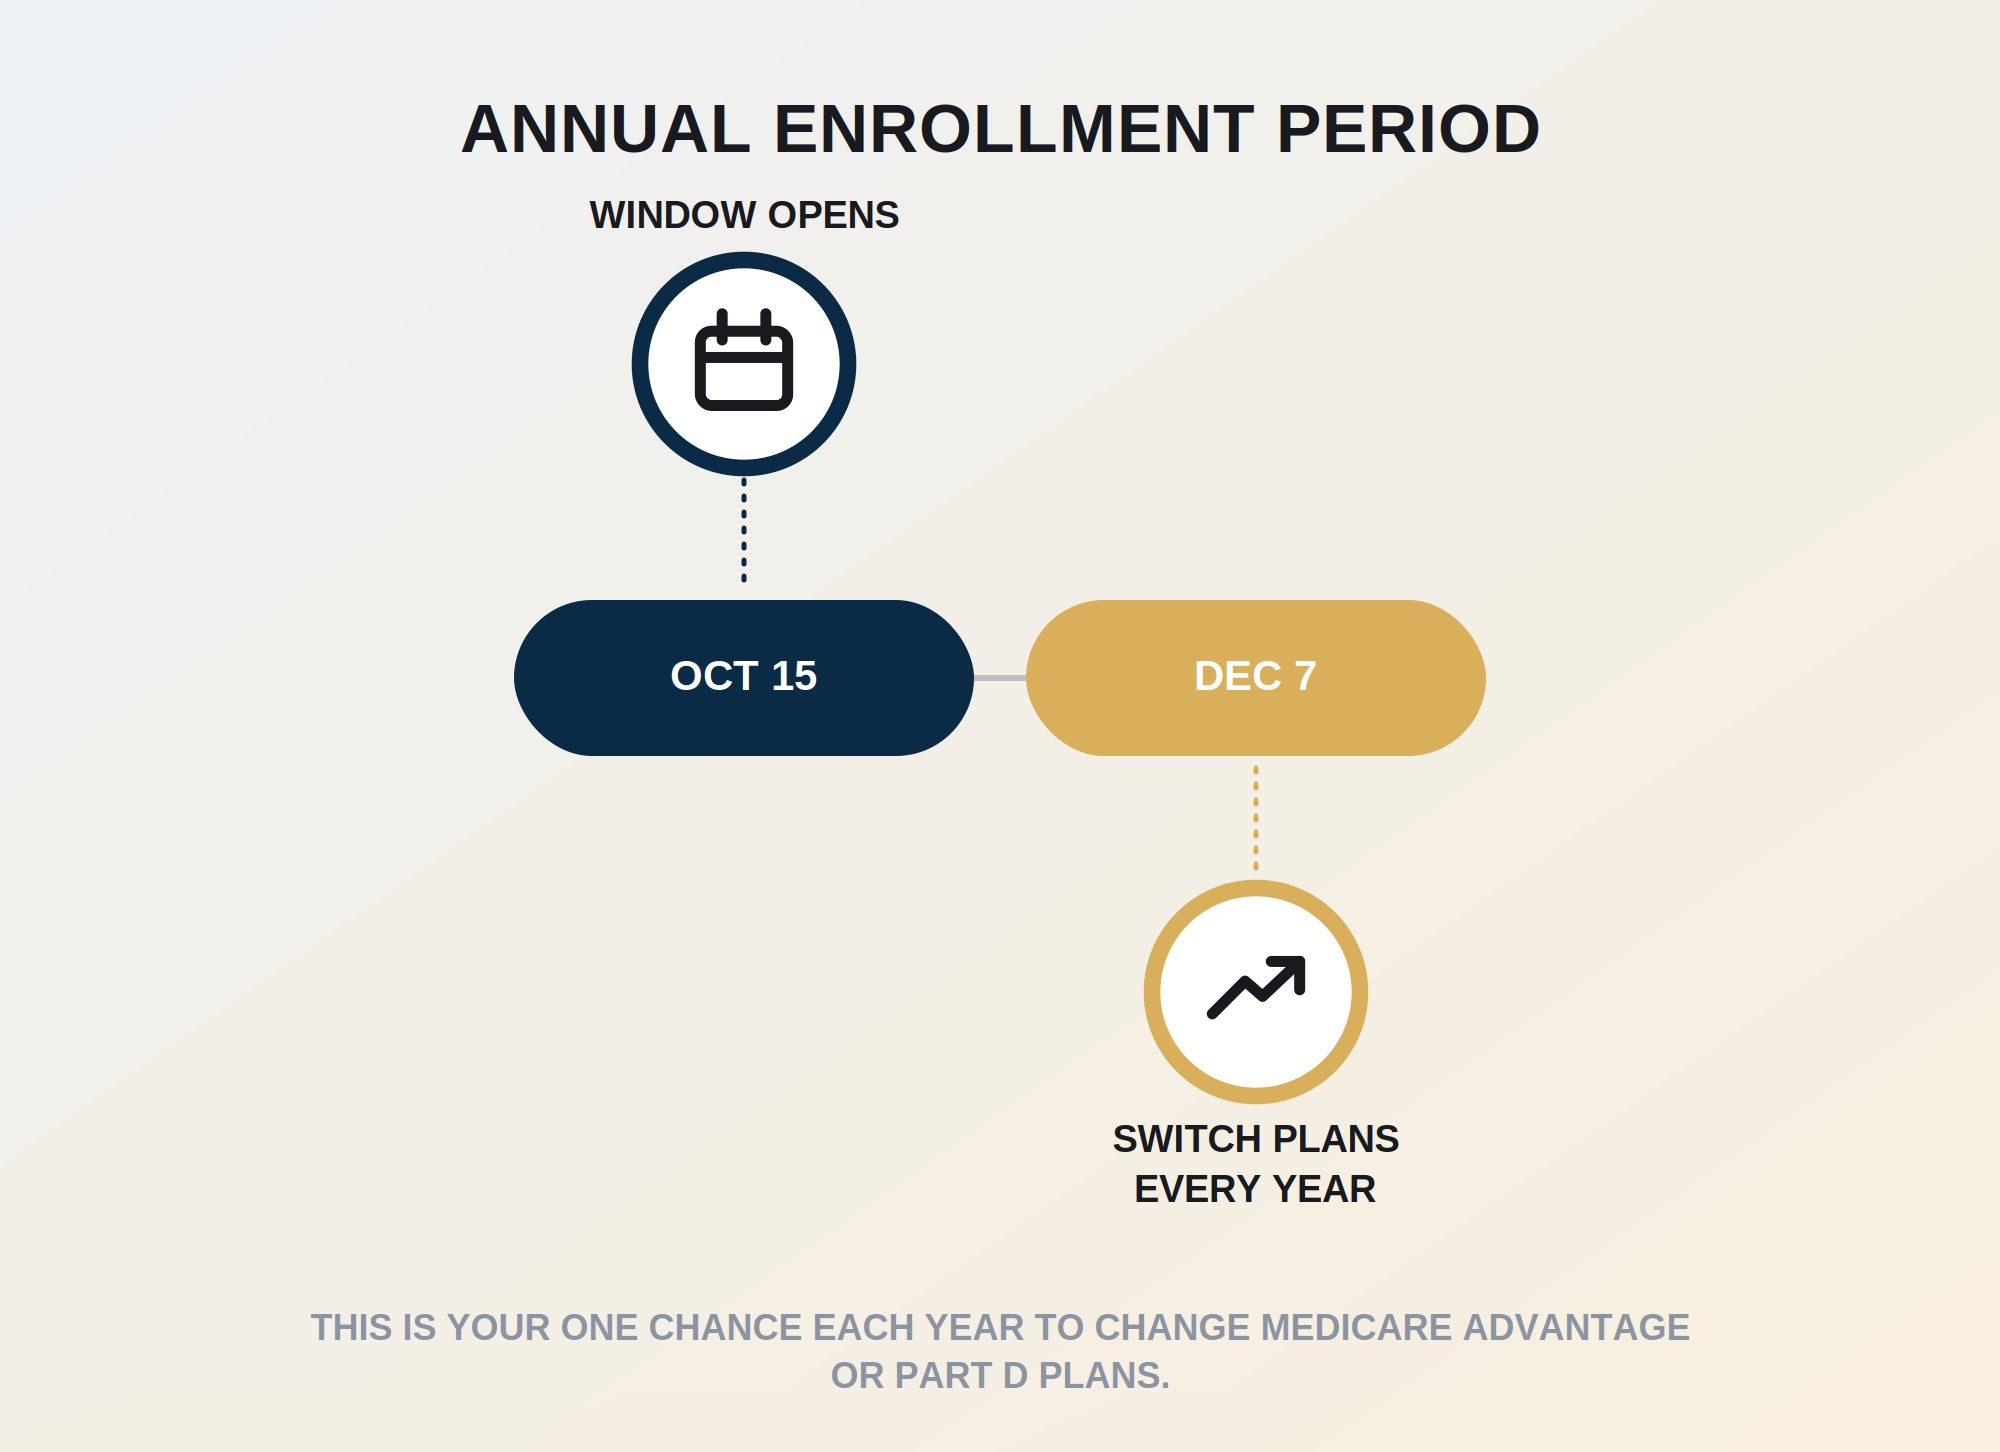
Once you’re already on Medicare, mark your calendar for October 15 through December 7 every year. This is when you can switch Medicare Advantage plans, move between Medicare Advantage and Original Medicare, or change your Part D drug plan. The Wall Street Journal has been blunt about this fall’s environment, noting that insurers are trimming benefits and raising out of pocket costs on a lot of plans heading into 2026, which makes this year’s open enrollment period more important to sit through carefully than in past years. Nearly seven out of ten Medicare beneficiaries don’t compare their options every year, according to research from KFF cited by Kiplinger, and that’s a mistake I see cost real money.
Why this matters more than people think
I’ve been doing this long enough to know that most people don’t get burned by a bad decision. They get burned by no decision, because they didn’t realize a deadline existed until it had already passed. Medicare penalties aren’t a one time fee. They follow you. A Part B penalty from missing your window at 65 can still be showing up on your bill at 80.
My advice is simple. If you’re within a few months of turning 65, or your employer coverage is about to end, or it’s October and you haven’t looked at your plan since last year, that’s your cue to have a real conversation with someone who does this for a living. That’s what our office is here for. We’re licensed across Ohio, North Carolina, South Carolina, Pennsylvania, and West Virginia, and we’d rather spend twenty minutes with you now than watch you pay a penalty for the next twenty years.
Tracy McManamon is President of One Source Benefits, LLC, an independent Medicare and insurance brokerage. Reach the office at 877-549-1212 or tmcmanamon@onesourcebenefits.com.