ONE SOURCE BENEFITS | MILITARY & VETERAN BENEFITS
The timing question trips up more retirees than almost anything else in the TRICARE and Medicare relationship. Everyone eventually learns they need Part B, but when depends entirely on your specific situation, and getting the timing wrong is one of the more expensive mistakes a retiree can make. Here’s how to figure out which timeline actually applies to you.
If You’re Already Retired and Approaching 65
This is the most straightforward case. You get a seven-month Initial Enrollment Period built around your 65th birthday: three months before, your birthday month, and three months after. Enroll anywhere in that window and Part B starts on schedule, keeping your TRICARE For Life coverage active without a gap.
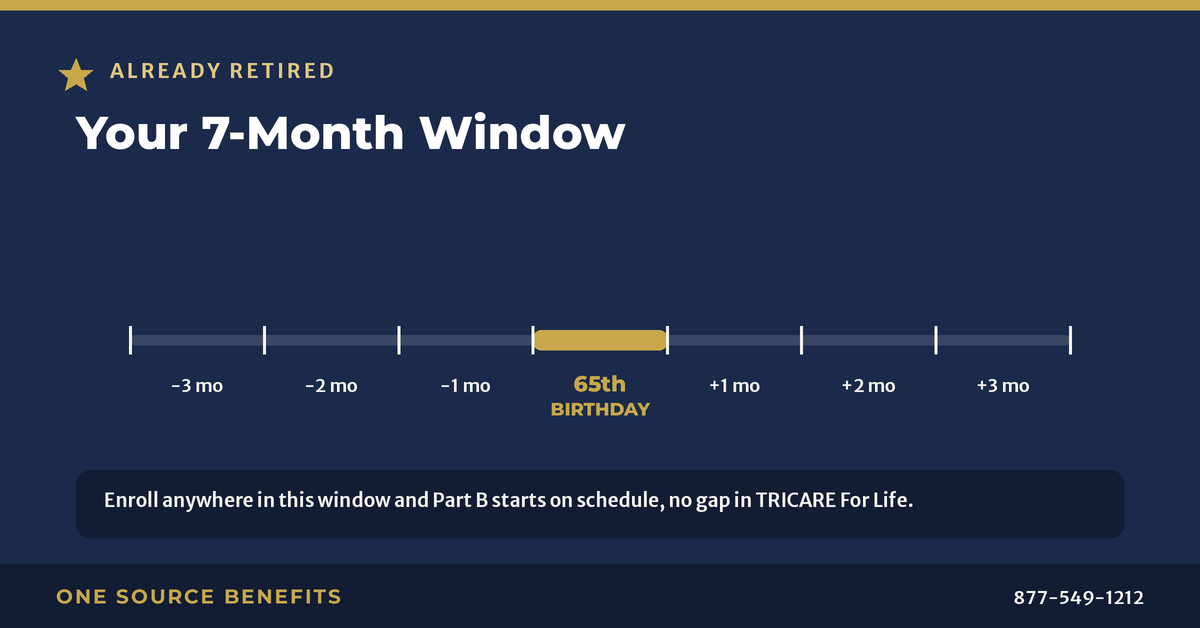
The mistake to avoid here isn’t complicated, it’s just easy to let slip. Mark the window on a calendar the day you read this, not the week your birthday arrives.
If You’re Still Working Past 65
This is where the timeline changes. If you’re still employed and covered under a group health plan through that job (not TRICARE alone), you may be able to delay Part B without penalty until that employment or coverage ends. Once it does, you get an eight-month Special Enrollment Period to sign up.
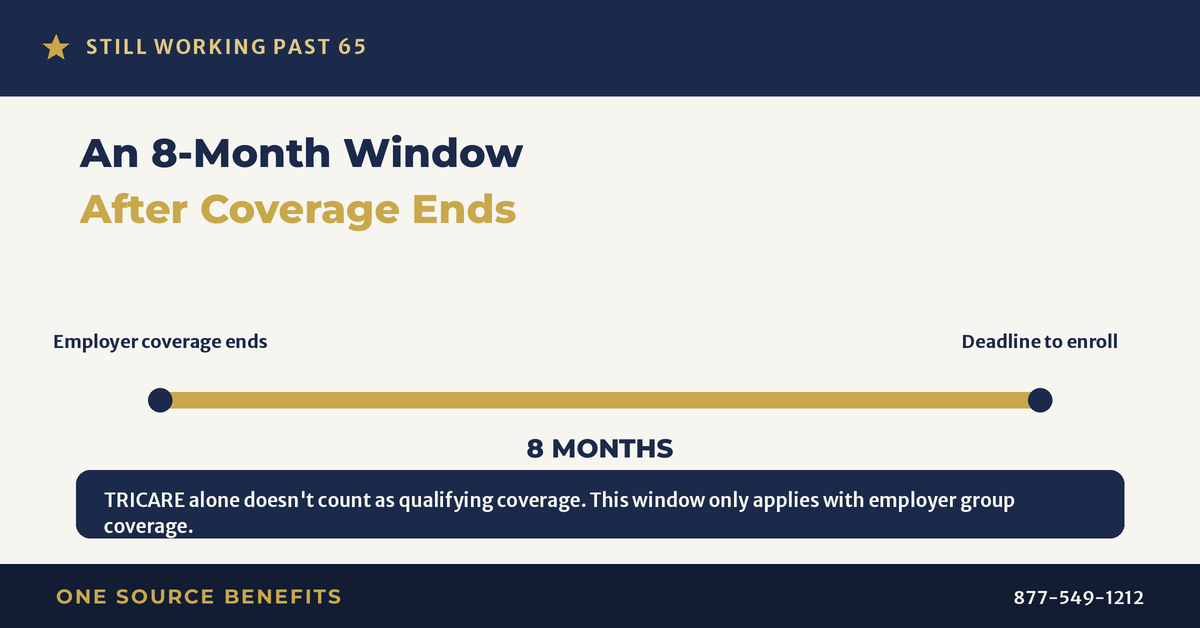
The detail that catches people off guard: TRICARE alone doesn’t count as the kind of employer coverage that qualifies you to delay Part B. If your only coverage past 65 is TRICARE, the standard enrollment window still applies, working past 65 doesn’t extend it the way employer group coverage does.
If You’re Retiring at or Near 65
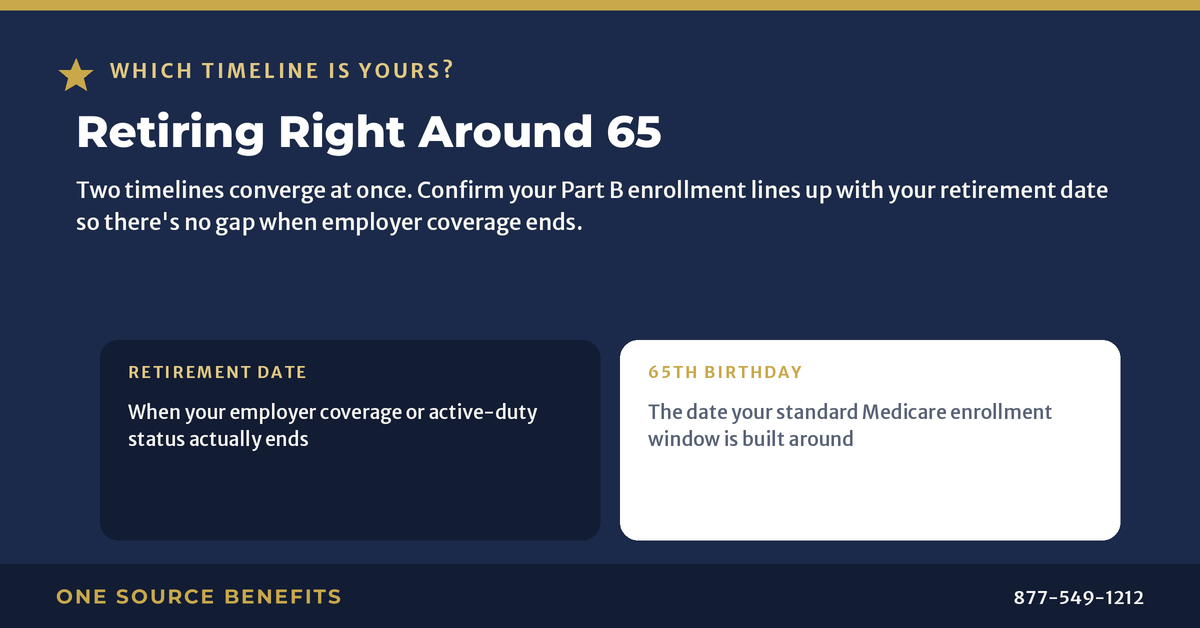
Retiring right around your 65th birthday means two timelines are converging at once, and it’s worth mapping them out ahead of time rather than sorting it out after the fact. If your retirement date and your 65th birthday land in the same general window, you’ll want to confirm your Part B enrollment lines up so there’s no gap between when employer coverage ends and Medicare picks up.
If You’re a Guard or Reserve Retiree
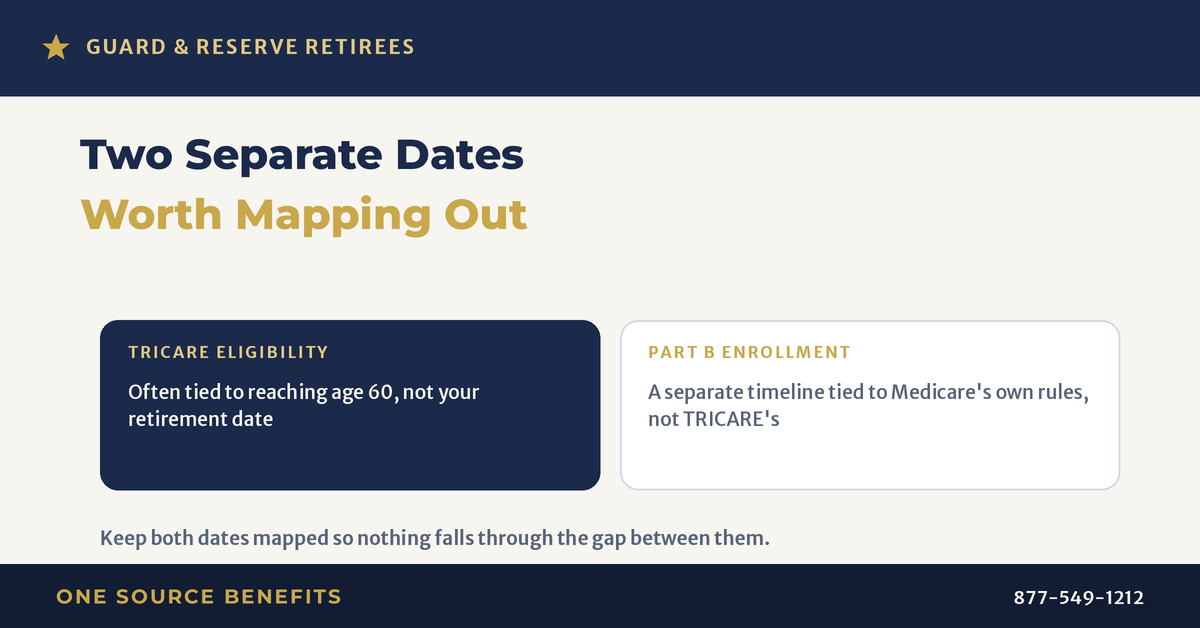
Guard and Reserve retirees often have a different timeline for when TRICARE eligibility itself begins, since it can be tied to reaching age 60 rather than the date of retirement. That timeline is separate from the Medicare Part B enrollment question, but it’s worth having both dates clearly mapped so nothing falls through the gap between them.
If You’ve Already Missed Your Window
This happens more than people expect, and it’s not the end of the road. There’s a General Enrollment Period each year, though missing your original window typically means a late enrollment penalty on your Part B premium that lasts for as long as you have Part B. The earlier this gets corrected, the smaller the ongoing cost.
Quick Recap
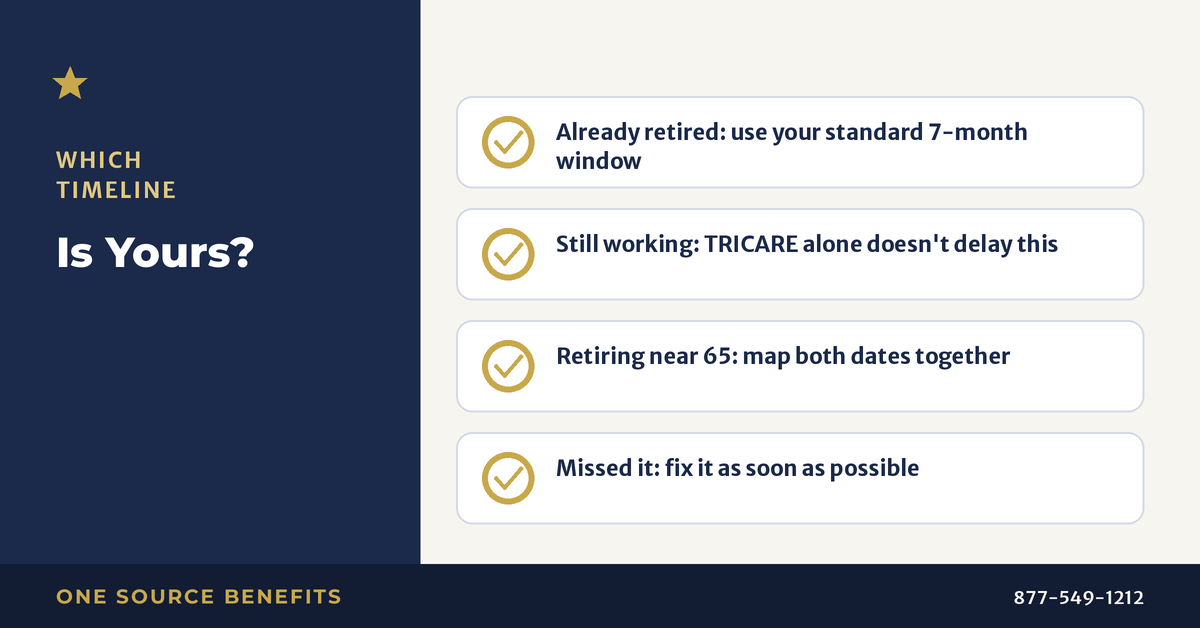
- Already retired at 65: Use your standard seven-month Initial Enrollment Period.
- Still working past 65: TRICARE alone doesn’t delay this. Only qualifying employer group coverage does.
- Retiring near 65: Map both dates together so there’s no coverage gap.
- Guard or Reserve: Confirm your TRICARE eligibility date separately from your Part B enrollment timing.
- Missed the window: Fix it as soon as possible to limit the penalty.
Not Sure Which Timeline Applies to You?
Every one of these scenarios has its own deadline, and mixing them up is exactly how retirees end up with a penalty they didn’t need. I’ve spent 36 years walking retirees through exactly this kind of timing question, and with family of my own who served, I take extra care getting it right for military retirees specifically.
Give me a call at 877-549-1212 and let’s figure out exactly which enrollment timeline is yours.